
Macro Linkages
Historical Win-Rate and Odds of the Semi Sector After Fed Rate Cut Cycles Begin
When the Federal Reserve pivots from raising rates to cutting them, everyone asks the same question: what happens to stocks now? More specifically, in the AI era, investors ask: what happens to semiconductors? Are they a reliable winner after the first cut, or does the sector’s cyclicality and high valuation risk turn the easing phase into a coin toss? History doesn’t give us a perfect script, but it does offer patterns—and those patterns give us a way to think about win rates and odds, rather than stories alone.
Sovereign Wealth Funds’ Rising Allocation Ratios to Strategic Semi Assets
Sovereign wealth funds (SWFs) live at the intersection of politics, macroeconomics, and long‑term investing. They exist to turn national surpluses—often sourced from commodities, exports, or foreign exchange reserves—into enduring wealth. In the 2020s, one asset class has moved from “interesting” to “strategic” in that mission: semiconductors. Chips are now seen as part of national security and industrial policy as much as financial opportunity. That shift has forced SWFs to think hard about how much risk they are willing to allocate to semi assets, and how that allocation fits into a world of changing interest rates, exchange rates, credit cycles, and commodity prices.
Drawdown Magnitude and Recovery Duration of Semis During USD Liquidity Crises
Semiconductor stocks have a habit of reminding investors that progress is not a straight line. Periods of explosive growth, fueled by new technologies and insatiable demand for chips, are often followed by brutal drawdowns when the macro environment turns. Among the most stressful of these episodes are USD liquidity crises—moments when dollar funding dries up, credit spreads widen, and global markets scramble for access to the world’s reserve currency. In those periods, the magnitude of semiconductor drawdowns and the duration of their recoveries tend to reflect not just sector-specific forces, but the broader macro linkage of interest rates, exchange rates, credit conditions, and commodities.
Semi Style Rotation Patterns During the Treasury Curve Dis-Inversion Period
When the US Treasury curve inverts—short‑term yields rising above long‑term yields—it doesn’t just spook bond investors. It quietly rewrites how equity sectors trade, including semiconductors. An inverted curve is a signal about future growth, funding costs, and recession risk. Semi stocks, with their mix of cyclical exposure and long‑duration growth narratives, respond in distinct ways. Within the sector, “style” rotation—between growth vs value, large vs small, equipment vs device makers—often emerges as investors reposition for a different macro regime.
Sensitivity Stress Test of CNY Fluctuations on Domestic Equipment Import Costs
Exchange rates are often discussed as abstract macro variables, but for firms that import equipment they show up as very concrete line items: higher or lower invoice amounts, changed project budgets, revisions to CapEx plans. In China, where many of the most advanced production tools and capital goods are still imported and priced in foreign currencies—especially dollars, euros, and yen—fluctuations in the renminbi (CNY) can have a direct and sometimes material impact on domestic equipment import costs.
Estimating the Pulse Effect of Post-2026 US Midterm Election Policy Expectations on Semis
Midterm elections don’t manufacture a single chip, but they can move the pulse of the entire semiconductor complex—through budgets, export controls, tax incentives, and energy policy. In 2026, that pulse is particularly important. AI, data centers, and onshoring drives have put semis at the center of U.S. industrial and security strategies. When investors look past the vote to what policy might come next, they’re not just guessing about politics; they’re re‑pricing interest rates, exchange rates, credit risk, and commodity demand. The question is: how do we estimate the pulse effect of post‑2026 US midterm election policy expectations on semis in a macro-linked way?
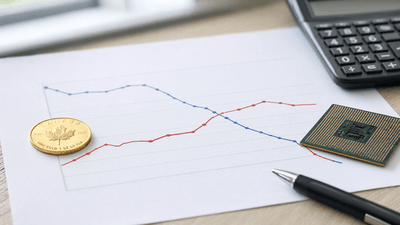
The Disappearance of Gold-Semi Negative Correlation During Crisis Periods
For years, gold and equities—especially high‑beta sectors like semiconductors—were seen as opposites in a portfolio. Gold was the safe haven; semis were the growth engine. When risk assets sold off, gold was supposed to rise, offering protection. When growth surged, gold might lag while semis rallied. That simple negative correlation made intuitive sense. Then crisis periods started to complicate the picture. In more recent shocks, gold and semis have sometimes moved together, or at least failed to deliver the clean inverse dance many investors expected.
The Complete Price Transmission Path from Commodities (Cu/Pd/Si) to Semi Manufacturing Costs
Semiconductors look like pure technology from the outside: nanometer nodes, transistor counts, AI performance metrics. Underneath the clean diagrams sits a very physical reality. Chips are built out of commodities—copper (Cu), palladium (Pd), silicon (Si), along with many others—and every move in those upstream markets eventually shows up in manufacturing costs. The transmission isn’t instant; it snakes through purification, wafers, interconnects, packaging, and energy before arriving at the P&L of a fab or a memory manufacturer.
Defensive Portfolio Strategies for Semi Stocks During VIX Spikes
Semiconductor stocks live at the intersection of technology excitement and macro stress. They benefit from long-term growth in AI, cloud, and electrification, but they also sit among the first sectors to get hit when volatility spikes. The VIX—the so‑called “fear index”—is a quick gauge of that stress. When it surges, correlation rises, liquidity can dry up, and cyclicals like semis often move sharply. Yet volatility episodes don’t have to turn into permanent damage for semi-heavy portfolios if you have a defensive playbook ready.
Impact of Narrowing US-China Yield Spreads on Net Foreign Capital Flows into Semi Sector
Yield spreads don’t manufacture a single chip, but they help decide who pays for the next fab and who doesn’t. For global investors, the difference between US and China government bond yields is a quiet steering wheel: when the spread is wide, capital leans one way; when it narrows, flows start to recalibrate. In 2020s markets—where semiconductors sit at the center of technology, trade, and policy—that steering wheel matters a great deal for where foreign capital lands inside the semi ecosystem.